The report needed evidence, not an assumption
The client was building a UK payments industry report. Publishing it meant answering two questions at once. How do SME merchants accept payments in store today, and how far has card and digital adoption progressed across sectors?
Neither question could be settled from secondary sources. A report is judged on what sits behind it, and what sat behind this one had to be verifiable and gathered on the ground.
A market research company can size a market from a model. Knowing what a merchant in Wigan is actually using to take payment is a different job, and it needs primary research done in person.
We ran three hundred surveys face to face, in the shops
Field research ran across London, Liverpool, Wigan, Telford and other UK cities, covering merchants of different business sizes and multi site footprints.
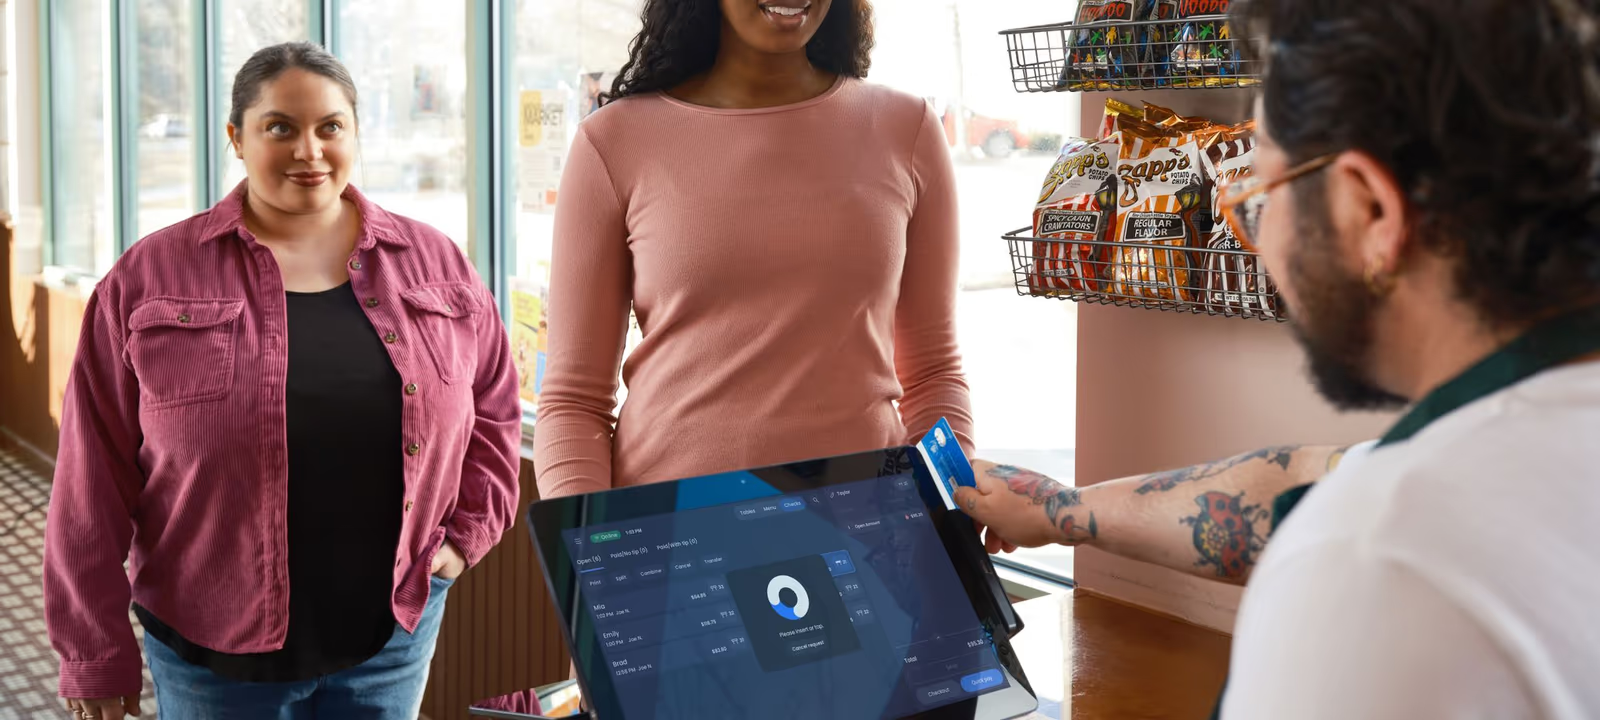
Each merchant survey captured the payment mix in use, debit, credit, cash and QR, and the transaction value and volume behind it. It also recorded the point of sale setup on the counter and whether QR was accepted at store level.
Eleven merchant categories were covered. That spread is what turns three hundred conversations into quantitative research a sector can be read from.
Every response was validated on the ground, including store front photographs, so the dataset could be audited rather than taken on trust. That is the part that makes a number usable in a published report.
Debit carries the market. QR is accepted but barely used
Debit cards dominated merchant sales, accounting for 52 percent of transaction value.
QR adoption was the finding that mattered most to the client. Only 29 percent of merchants accepted it, and it represented under 2 percent of transaction value. Acceptance and use are not the same thing, and the gap between them was the story.
The client took away a quality controlled, report ready dataset with sector level benchmarks. The method held well enough that the research has since scaled into three additional geographies.