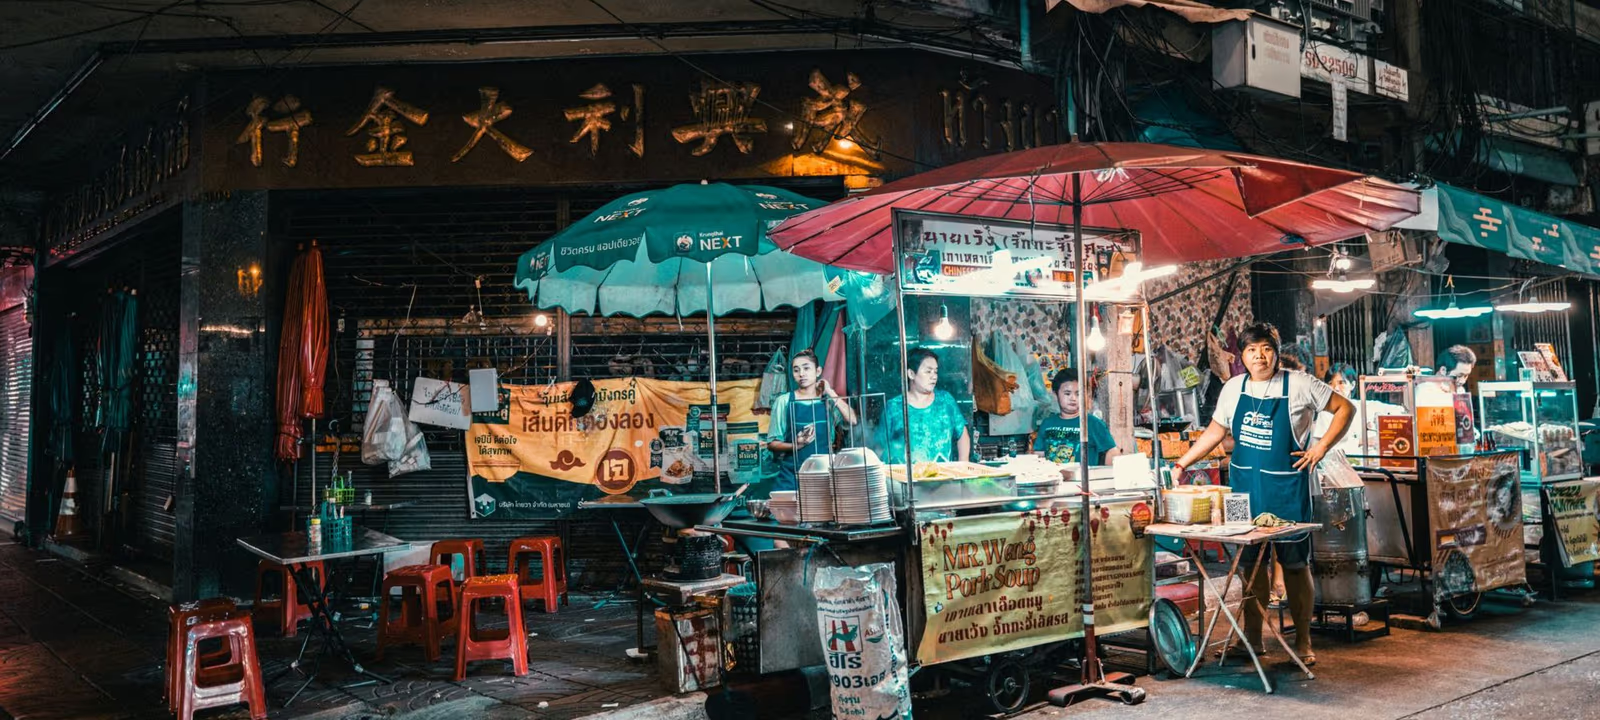
Thailand's long-tail SMEs, street vendors and mom-and-pop shops, sit outside formal bank credit because their data is too thin to underwrite and their loan sizes too small to price profitably under rate caps. Grab closed that gap using an already-built base of riders and merchants, transaction data instead of bank statements, and a daily repayment design, reaching an estimated 60% of long-tail merchants banks have not. Lazada and Shopee have since applied the same playbook.
Why are long-tail SMEs locked out of bank credit in Thailand?
The SME market breaks into tiers. Multinational and established local chains already carry bank credit lines. Below them is the long tail: street food vendors and small mom-and-pop operators, who make up the bulk of SME numbers by count, carry lower individual credit needs, and are the segment the banking system is not reaching. The addressable market for embedded lending was never 'SMEs' as a category; it is specifically this tier.
Two structural constraints keep banks out. Thailand's National Credit Bureau carries thinner records than bureaus in other markets, and much of the long tail has no bureau file at all. Bank of Thailand rate caps, roughly 25% for personal loans and 33% for nano loans, leave little room to price for the higher servicing cost per baht lent on small loan sizes. Underwriting a segment banks can barely see, at a rate they can barely afford to lend at, does not clear a bank's return threshold even where demand is real. Embedded platform lending reaches an estimated 60% of long-tail merchants where the banking system has not.
- 01
Embedded distribution
An already-built base of riders and merchants keeps acquisition cost near zero.
- 02
Behavioural underwriting
Transaction data makes underserved, bureau-thin borrowers underwritable.
- 03
Funding economics
Cheap enough funding to leave sufficient margin once rate caps apply.
How did platforms turn distribution into a lending advantage?
Grab's SME lending began with smartphone financing for drivers, scored off platform activity and income data. A 9,000-baht phone, conventionally repaid at 3,000 baht a month over three months, was instead restructured into a 100-baht daily deduction from the driver's wallet, reframed as the cost of one extra ride rather than a monthly bill.
"100 baht a day is one extra ride, and it pays for itself," said the former Head of Business Development at Grab interviewed for this report. No promotional pricing was needed. What mattered was removing friction: one tap to apply, disbursement straight into an existing wallet, against a bank process that starts with an ID submission and a wait. Thailand became Grab's number-one SME-lending market across every country it operates in.
One case: a hotel worker whose job closed during COVID started a small som tam stall and moved onto the Grab platform for credit. A first loan grew the business; loan size increased as the business proved itself; three to four years later, the operation had grown into a chain of four to five restaurants near Pattaya, each proven repayment cycle earning the next, larger loan.
How does behavioural underwriting actually work?
Platform credit scoring runs on GMV activity, order and sales frequency and behavioural trend data, rather than the bank statements a bank would ask for, and it typically requires at least three months of consistent platform activity before a merchant can access even a small first loan. Cash loans were priced with interest applied monthly but collected daily, which lowers the effective rate a borrower actually pays and changes how fast a lender sees trouble: a defaulting borrower shows up within three to four days under daily collection, versus roughly a month under a bank's billing cycle.
"Our NPLs of this subprime sector were lower than banks'," the expert said. Blended non-performing loans ran below 2%, with more established borrowers under 1% and newer borrowers at three to four percent, managed by lending less at shorter tenure until a track record exists. The model's edge has a boundary: risk pricing is reliable for microlending and one-to-two-year tenures, tested since roughly 2018 to 2019, but gets materially harder to price accurately at longer tenures, where income variability across SME and gig-worker occupations increases uncertainty.
| Acquisition cost | Funding cost position | |
|---|---|---|
| Platform-native lenders | Near-zero, borrower already on platform | Constrained by rate caps, no funding-cost edge |
| Banks | High, branch and relationship-led | Structural advantage, cheapest cost of funds |
| From-scratch fintech entrants | High, no existing distribution base | Same rate-cap constraint, no offsetting advantage |
What drives lending economics and competitive moats?
Acquisition cost was close to nothing, because the borrower already existed as a rider or merchant on the platform before ever being offered a loan, a fundamentally different cost structure than a lender building a borrower base from a cold start. Funding cost explains the rest of the margin: the nominal cap under Thailand's Nano Finance licence sits at 33%, but because that rate is amortised through daily deductions, the effective rate realised is closer to 16 to 17%, the spread that has to cover funding cost, credit losses and operating cost.
Full regulatory compliance is available to any entrant, but it makes the application process long enough that applicants abandon it partway through, going to informal lenders instead. Competitors building from scratch, Ant Financial among them, carry that same onboarding cost without Grab, Shopee and Lazada's existing distribution advantage, a dynamic worth weighing against how partner and ecosystem selection gets scoped for any lender evaluating this market, including how it relates to how quickly a lending platform's underlying payment infrastructure can actually scale.
Who is best positioned to capture the SME lending opportunity?
Four types of lender operate in this market today. Banks hold funding-cost and balance-sheet advantages but are constrained by currently low approval rates, high household debt and rate-capped economics on small loans. Platform-native lenders carry near-zero acquisition cost and proprietary transaction data as their core advantage. From-scratch fintech entrants carry full onboarding and marketing cost without an existing distribution base. Informal lenders continue to absorb borrowers who abandon a formal application partway through.
Looking three to five years out, banks are positioned as the player structurally best placed to lend at scale as current cyclical constraints ease, since they retain balance-sheet capacity platform-native lenders are not trying to build. No single player type holds every advantage at once: platform-native lenders lead on distribution but not funding cost, and banks lead on funding cost but not, yet, distribution into the long tail.